
You are currently viewing Gifting Coins: Form 709, the Annual Exclusion and Carryover Basis
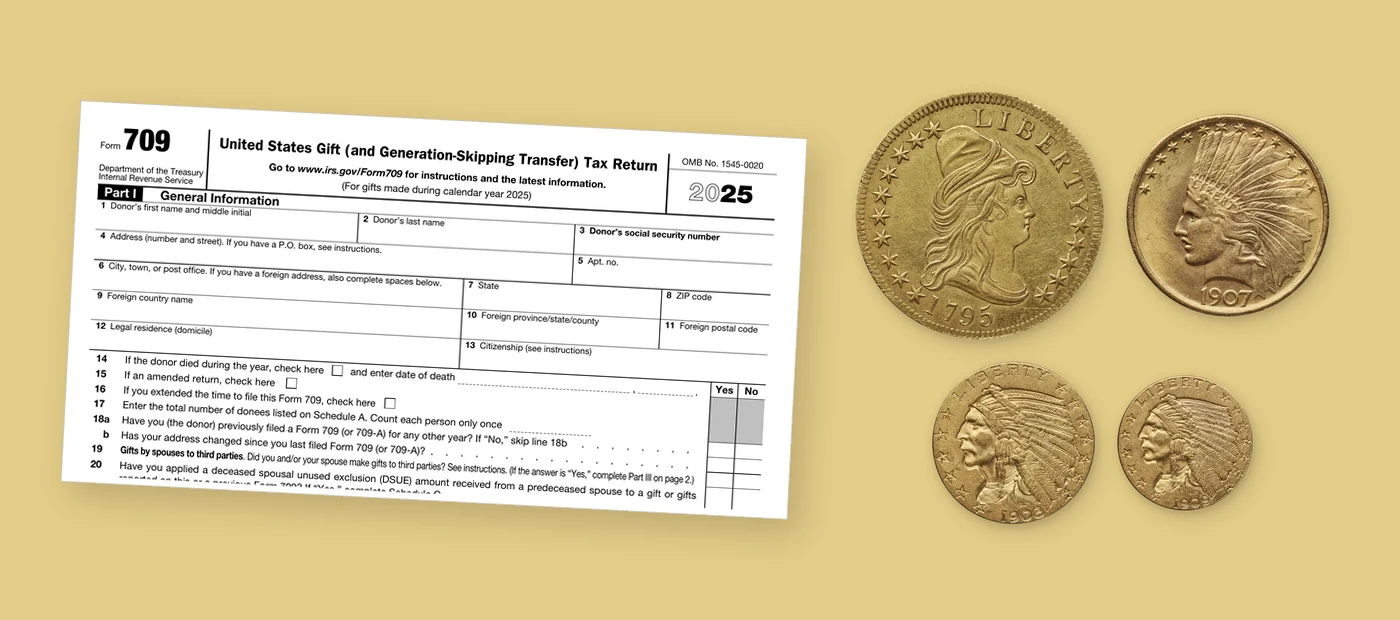
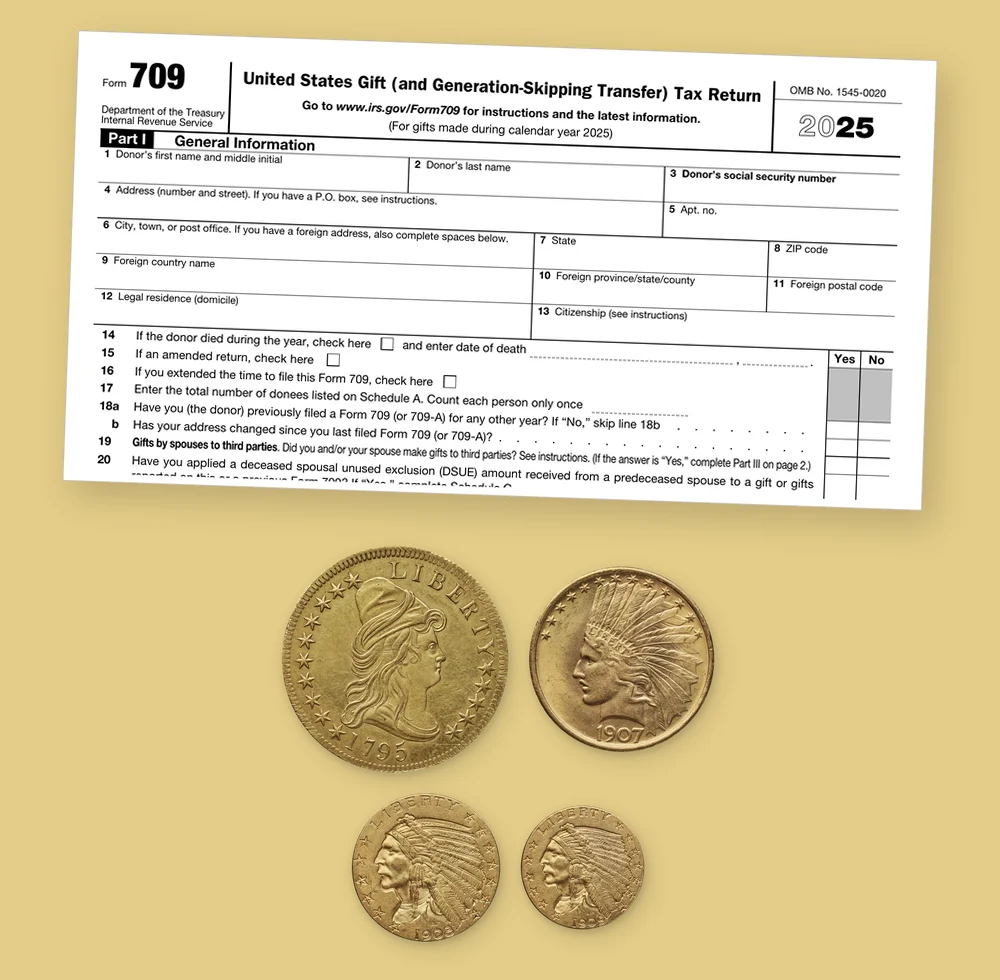
IRS Form 709 (2025), page 1, from irs.gov; U.S. government work, public domain (IRS logo not shown). Coin photos: Bibliothèque nationale de France, Département des Monnaies, médailles et antiques (Gallica), public domain, via Wikimedia Commons (library media 42723).

Gifting Coins: Form 709, the Annual Exclusion and Carryover Basis

  • Post published:
  • Post category:Articles
Gifting coins: IRS Form 709 with 1795 Turban Head $10 eagle, 1907 Indian Head $10 eagle, 1908 Indian Head $5 half eagle and 1909 Indian Head $2.50 quarter eagle

The Short Answer

When gifting coins, each gift is valued at fair market value on the date of the gift, not at face value and not at what you paid. For 2026, you can give up to $19,000 per recipient without filing a gift tax return, or $38,000 when spouses split gifts. If your gifts to any one person in a year go over the annual exclusion, you file Form 709 by April 15 of the following year. Download IRS Form 709 (fillable PDF).

Filing usually does not mean paying. The excess counts against your lifetime basic exclusion amount, which is $15,000,000 for gifts made in 2026. What the recipient does get is your cost basis, so a later sale can carry a larger capital gain than inherited coins would.

Not tax or legal advice. This guide is general information about federal rules as of November 2026. Tax law changes and every situation is different, so confirm the details with your CPA, tax attorney or estate attorney before you file, sign or transfer anything.

Decorative gold separator bar

When a Gift of Coins Needs Form 709

SituationForm 709?
Coins worth $19,000 or less, given outright to one person in 2026 (with any other gifts to that person)No
Coins worth more than $19,000 to one person in 2026Yes, by April 15, 2027
You and your spouse split gifts to stay within $38,000 per recipientYes, because the election to split gifts is made on Form 709
A gift of a future interest, such as coins placed in a trust the recipient cannot use nowYes, whatever the amount
Coins given to your spouse who is a U.S. citizenGenerally no, because of the marital deduction

The Form 709 instructions cover the exceptions, including gifts to a spouse who is not a U.S. citizen. An extension of time to file your income tax return also extends the time to file Form 709. The donor, not the recipient, is normally responsible for any gift tax, as the IRS gift tax FAQ explains.

Decorative gold separator bar

Valuing Coins on the Date of the Gift

Fair market value is the price at which the coins would change hands between a willing buyer and a willing seller, neither under any compulsion and both reasonably informed. For coins, that means:

  • Bullion such as American Eagles and gold or silver bars follows the metal market, so the value is tied to spot prices on the gift date.
  • Rare and collectible coins are valued by date, mint mark, grade, certification and recent comparable sales. A price guide or a retail asking price is not the same as fair market value.
  • Gold coins with a face value, such as a $20 Saint-Gaudens, are valued at their market value, which is far above face.

The IRS lists copies of appraisals among the documents to include with Form 709. A gift that is adequately disclosed on the return, with a description of the coins and how they were valued, generally starts the three-year period the IRS has to question that value. An itemized written appraisal is the simplest way to show it.

Decorative gold separator bar

Carryover Basis: What the Recipient Inherits From You

When you give coins during your lifetime, the recipient generally takes your adjusted basis, meaning what you paid plus certain costs. Their holding period includes yours. Two refinements, covered in Publication 551:

  • If the coins were worth less than your basis on the gift date, the recipient uses that lower value to figure a loss on a later sale.
  • If you paid gift tax, the recipient may add the part of the tax that relates to the coins’ appreciation.

When the recipient sells, long-term gains on coins are taxed as collectibles gains, at up to 28% federally. Compare that with coins inherited at death, which generally get a basis equal to their date-of-death value. Our step-up in basis guide explains that rule.

Give the recipient your records. Purchase invoices, dates and the appraisal of the gift-date value all go in their file. Without them, proving basis years later is difficult.

Decorative gold separator bar

Give Now or Leave Coins Through Your Estate?

For coins that have gained a lot of value, the carryover basis can cost the recipient more income tax than the gift saves. Coins bought recently, or bullion bought near today’s prices, carry little built-in gain. Many families give some coins now and leave highly appreciated pieces to pass through the estate. That is a planning decision for you, your CPA and your estate attorney. For a broader view, see our guide for the wealth advisor.

Decorative gold separator bar

How American Rarities Helps

Founded in 1990, American Rarities has purchased over $400 million in rare coins, bullion and collectibles. We are ANA Life Members, an authorized PCGS, NGC and ANACS dealer, rated A+ by the BBB and 4.7 stars on Google. For a gift, we can:

  • Prepare a formal, itemized written appraisal of the coins as of the gift date, for a fee, with photos, grades, certification numbers and the comparable sales used.
  • Give a free appraisal and written offer if some of the coins will be sold instead of given.
  • Value bullion and rare coins separately, so the return shows how each was valued.

To get started, text photos to 720-600-4740, email staff@americanrarities.com or use the form below.

Four Steps to an Appraisal

  1. 1
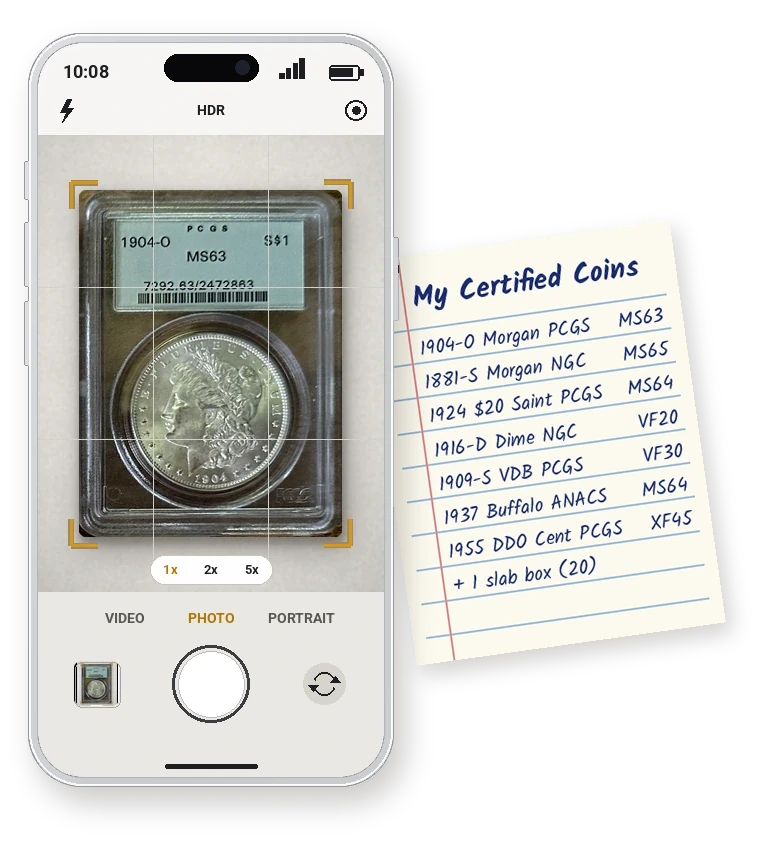
    Silver-white smartphone camera photographing a PCGS-certified 1904-O Morgan silver dollar graded MS63 beside a handwritten inventory list of PCGS, NGC and ANACS slabbed coins, for a free appraisalSilver-white smartphone camera photographing a PCGS-certified 1904-O Morgan silver dollar graded MS63 beside a handwritten inventory list of PCGS, NGC and ANACS slabbed coins, for a free appraisal

    Send Photos and/or a List

    Send photos or a list: text photos to 720-600-4740, email staff@americanrarities.com or use the form below. Tell us the gift date and whether you need a formal report.

  2. 2
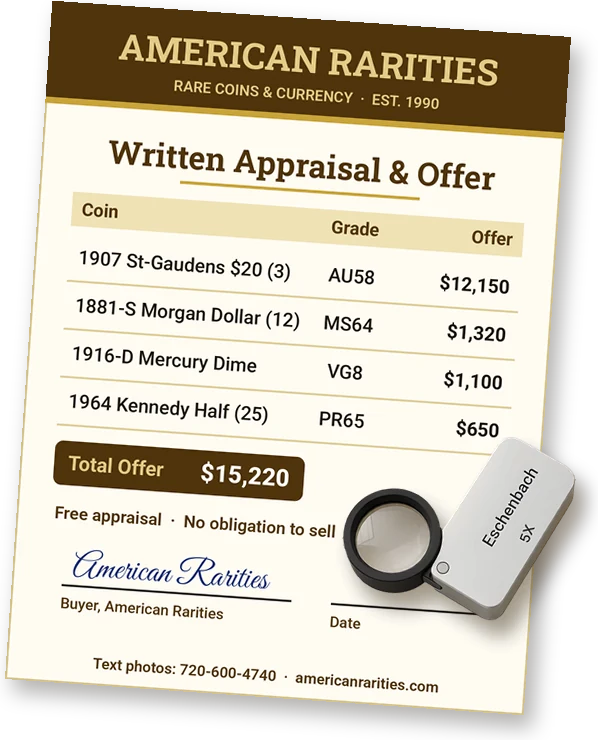
    Eschenbach 5X folding loupe resting on an American Rarities written appraisal and offer sheet listing U.S. coins, grades, offer amounts and a total offerEschenbach 5X folding loupe resting on an American Rarities written appraisal and offer sheet listing U.S. coins, grades, offer amounts and a total offer

    Free Appraisal and Written Offer

    Appraisals are usually done within 24 hours, though larger collections may take longer. If so, we’ll let you know. A formal gift-date appraisal report is a separate, fee-based document.

  3. 3
    FedEx delivery truck beside a taped, padlocked carton addressed to American Rarities, or an American Rarities buyer examining gold coins with a loupe at a home visitPhone version: FedEx delivery truck with a taped, padlocked carton addressed to American Rarities, or our buyer examining gold coins with a loupe at a home visit

    Ship or Meet

    Ship fully insured at our expense, or meet us in person. We can meet you at your bank. If you decline our offer, we return your items fully insured.

  4. 4
    Banded stack of hundred-dollar bills labeled CASH, an American Rarities check labeled CHECK, and a bank-to-bank transfer labeled ACH and WIRERow of payment options labeled CASH, CHECK and ACH WIRE: a stack of hundred-dollar bills, an American Rarities check and a bank-to-bank transfer

    Get Paid

    If you accept our offer, you choose how you are paid: cash, check, ACH or wire.
Decorative gold separator bar

Gifting Coins: Frequently Asked Questions

Do I have to pay gift tax when I give coins?

Usually not. Gifts over the annual exclusion are reported on Form 709 and reduce your lifetime basic exclusion amount, which is $15,000,000 for 2026. Tax is due only after that amount is used up.

Is a gold coin with a $20 face value valued at $20?

No. Coins are valued at fair market value on the date of the gift. A $20 gold piece is worth far more than its face value.

Can my spouse and I give $38,000 in coins to one person?

Yes, in 2026, by electing to split gifts. The election is made on Form 709, so a return is required even though no tax is owed.

What basis does the person receiving my coins get?

Generally your basis, which is what you paid plus certain costs. If the coins were worth less than your basis on the gift date, a different rule applies to losses.

When is Form 709 due?

By April 15 of the year after the gift. An extension of your income tax return also extends the time to file Form 709.

Can you appraise coins for a gift tax return?

Yes. We prepare formal, itemized written appraisals as of the gift date for a fee when there is no sale, and we give a free appraisal and written offer when coins are being sold.

Decorative gold separator bar

Free Appraisal for Coins You Plan to Give

Email, Text, or Use This Form To Send Us Your Inventory List or Pictures


Upload clear photos of fronts and backs and we'll reply with a free appraisal.

    Decorative gold separator bar

    Leave a Reply